Building a €3 Customs-Compliant EU Returns Policy
17.08.2026 · 13 min read

Most e-commerce brands based outside the EU hit the same wall as they scale in Europe: since 1 July 2026 every parcel sent to an EU customer pays a €3 duty per item line, and the replacement you ship after a return pays it all over again. An EU customs compliant returns policy template therefore needs to do more than explain refund timing: it should account for that duty on imports and returns, inform customers of their withdrawal rights and return conditions under EU regulations, include the two-step electronic withdrawal function required by Directive (EU) 2023/2673, set out when and where you provide local return addresses in key EU markets, and define how returned goods are verified and matched with product identifiers in customs declarations ahead of 1 November 2026.
For international e-commerce sellers and marketplaces - especially small to midsize brands selling cross-border into the EU and UK - the cost of getting this wrong is immediate. A return crossing the border back to you often costs more than the goods you recover, and without a local return address the marketplace makes the decision for you - refunding the customer and charging your account while the product stays where it is.
If you want to stay profitable in the EU, you have to change how you handle returns. That means building a policy tailored to the relevant legal standards for your business model and markets served, and an operating flow that covers customs clearance, withdrawal compliance, local return routing, return verification and grading, and the marketplace integrations needed to run EU-compliant reverse logistics without double duties, unnecessary refund losses, or avoidable penalties.
Why this matters now
The regulatory picture shifted within a single quarter, and the changes are already live.
Law and regulation:
- Since 1 July 2026 the EU applies a temporary €3 duty per item line on consignments with an intrinsic value up to €150 imported from outside the Union (Council Regulation (EU) 2026/382). The measure runs until 1 July 2028, when normal tariff rates take over.
- The duty is charged per tariff line, not per parcel. The Council's own example: a parcel containing one silk blouse and two wool blouses counts as two separate items because they fall under different tariff sub-headings, so the duty is €6.
- It applies to distance sales of imported goods and targets sellers registered for IOSS in particular. It is charged to the business - the seller, importer or their representative - not collected from the consumer at the door. This is your cost, not their surprise on delivery.
- Since 19 June 2026 an electronic withdrawal function is mandatory (Directive (EU) 2023/2673, new Article 11a of Directive 2011/83/EU). It is not a one-click mechanism: the law requires two steps - an expression of intent to withdraw, followed by confirmation. These obligations arise under consumer protection laws and require businesses to clearly communicate the withdrawal process. The obligation depends on whether you direct your offer at EU consumers, not on where your company is established, and it covers contracts concluded through third-party platforms. A clear return and refund policy should also be visibly displayed on the seller's site, ideally in the website footer, for maximum visibility and legal compliance. Some national rules may also conspicuously post any no-refund or restrictive return terms before purchase. When properly presented to the customer, these requirements can become legally binding terms of the sales relationship.
- Product identifiers (PID) in customs declarations become mandatory on 1 November 2026; they can be supplied voluntarily from 1 July 2026, with no penalties during the transition.
- More charges are queued up: an EU handling fee of €2 (not expected before November 2026) and national fees such as Italy's €2 charge from 1 July 2026.
Logistics and margin:
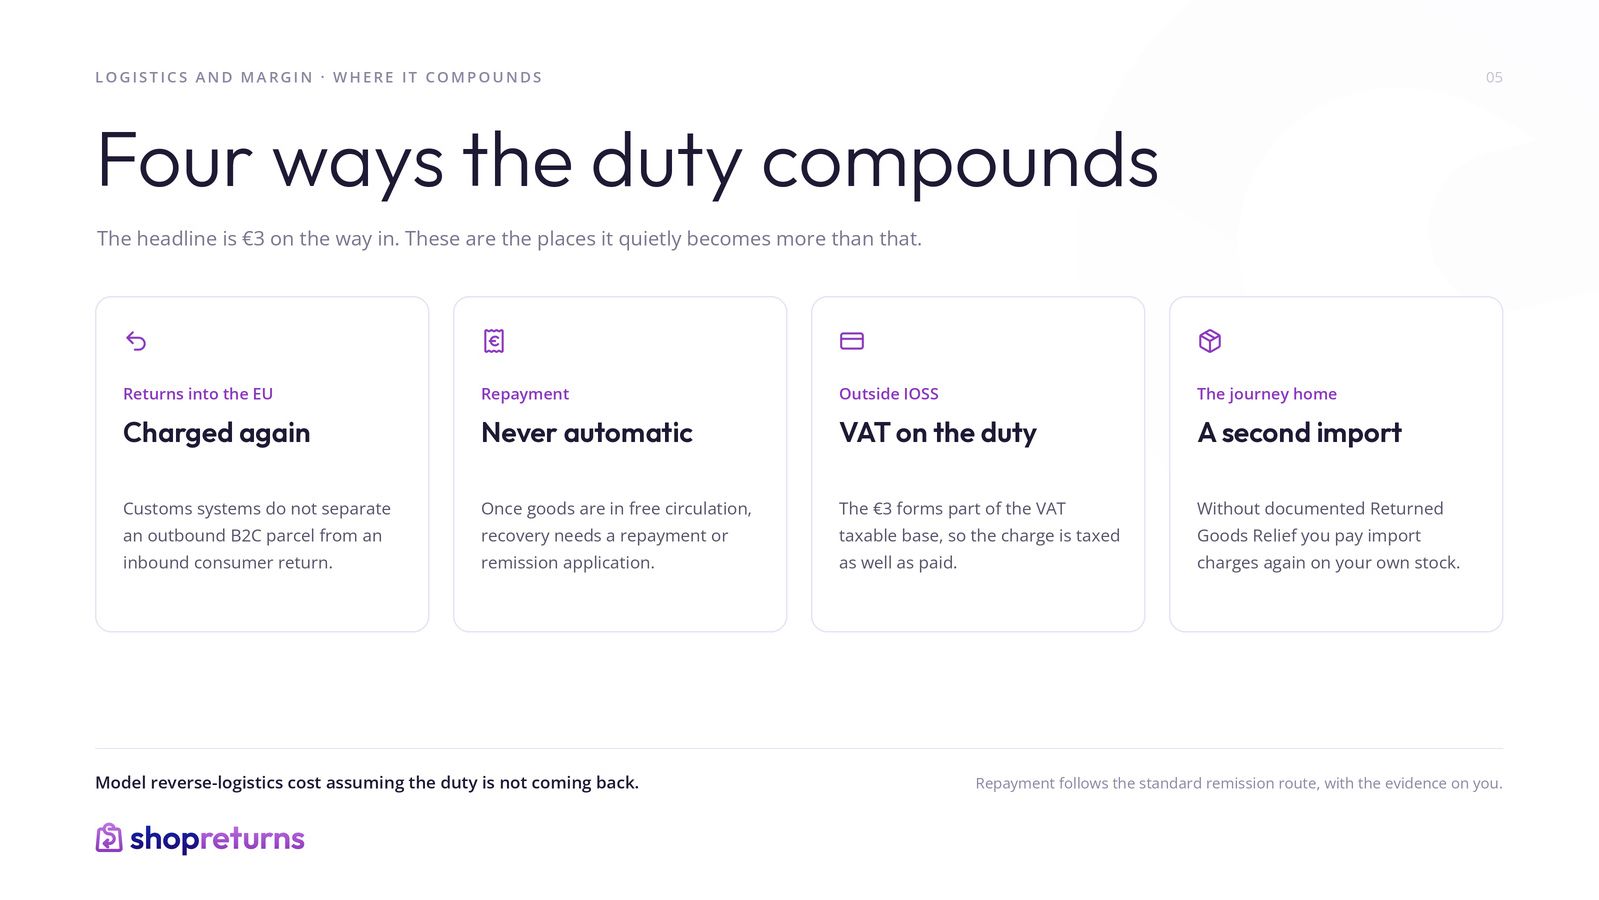
- Customs systems do not currently distinguish an outbound B2C shipment from an inbound consumer return, so the €3 duty also applies to returns entering the EU.
- Repayment of the duty is not automatic once goods have been released for free circulation. Recovery follows the standard application route for repayment or remission of customs debt, with the full evidential burden on you.
- Outside IOSS, the €3 duty forms part of the VAT taxable base - you pay VAT on the duty.
- A return travelling from the EU back to your home country is an import on that side. Without properly documented Returned Goods Relief you pay import charges a second time on your own stock.
Ignoring this hits operating margin directly and puts your position in key EU markets at risk.

What usually goes wrong with refund laws
- Exchanges shipped from a warehouse outside the Union. Every replacement is a fresh import and pays €3 again - and a multi-item order pays a multiple of €3. The policy promises free unlimited exchanges; the operation pays the duty twice.
- No local return address, and automatic returnless refunds. For merchant-fulfilled orders shipped from abroad, Amazon requires either a domestic return address or a returnless refund for items up to €25 or £20 including VAT. Above that threshold you have two calendar days (down from five) to offer a returnless refund, a domestic return option, or a prepaid international label. Miss the window and Amazon refunds on your behalf and charges your seller account.
- Refund timing tied to physically receiving the parcel abroad. The Consumer Rights Directive requires reimbursement within 14 days of being informed of the withdrawal, with a right to withhold until the goods are received back or proof of dispatch is provided. Once the parcel is crossing a border, that timeline stops being realistic. Your return policy should also state who pays return shipping costs and set out any time limits clearly, so the legal withdrawal period and any voluntary return window are not confused and the return process stays transparent and compliant.
- No compliant withdrawal function. If the information obligation is not met, the right of withdrawal does not expire after 14 days but after 12 months and 14 days. Not having a return policy, or failing to provide the required withdrawal information in it, can extend withdrawal rights to 1 year. A customer can return used goods almost a year later - and if customers are not clearly told about their statutory rights, across thousands of transactions that is systemic risk, not an edge case.
- No grading rules and no product data. Without written rules, the restock-or-scrap decision gets made at the unpacking table, nobody can tell finance what a return actually cost, and from 1 November 2026 the PID requirement in customs declarations lands on top of it.
Where the two groups differ: for brands shipping from the UK the dominant problem is double duty on exchanges plus the return leg back into Britain. For sellers in the US, Canada and Australia the dominant cost is return freight itself - an individual transatlantic return can exceed the value of the goods being recovered, so the product sits physically in Europe but is economically lost. The fix is the same in both cases: the return should never cross a border.

How the return and refund policy process should work
A properly designed EU returns flow looks like this:
- Step 1: Return registration. The customer registers the return through the One-Click-Return plugin, which satisfies the two-step withdrawal requirement under
Article 11a, and receives a local carrier label in their own country, while orders for digital products are handled separately where no shippable return exists.
- Step 2: Local collection inside the EU. The parcel goes to a drop-off point or receiving hub in the customer's market. The return never leaves the Union, so it triggers neither a customs event nor international freight cost.
- Step 3: Verification within 48 hours. Quality assessment, EAN scanning, photo documentation and an ERP record. Verification should confirm items are in new and unused condition, in unused condition, with original packaging, tags attached, and labels attached where applicable before resale, an exchange under your exchange policy, store credit, a full refund, or another outcome is approved. You release the refund on local confirmation, comfortably inside the statutory 14 days and inside marketplace response windows.
- Step 4: Disposition decision. The item goes back on sale in the EU, moves to resale, is donated, or - if it genuinely has to return home - joins a single consolidated bulk shipment with one customs clearance instead of hundreds of individual parcels. Under a standard return policy, screen out non returnable items before teams process returns; the policy should also state whether sale items are accepted and whether a restocking fee applies to permitted voluntary returns, while exceptions often include personalized items and perishables, which are typically non refundable.
What customer satisfaction means for your team
The financial effect is the easiest to describe. A replacement fulfilled from stock already inside the EU is not an import, so it never pays the €3 a second time, and the worst case - money refunded while the goods are gone - stops happening at all. Where stock genuinely has to go home, it goes under one customs procedure rather than hundreds.
That turns into a predictable operating rhythm. A return closes within 48 hours of reaching the local address instead of weeks later, once clearance and international transit are done with it, and the scramble to hit two-day marketplace response windows disappears because the parcel is already in the right country.
It also protects the customer promise. A local label, no contact with customs, a fast refund - you can keep all of it precisely because the operation behind it is cheap to run. Worth setting one expectation explicitly: releasing a refund and the money appearing on the customer's card are two different events, and the bank leg adds time after your part is finished. Saying so upfront removes the single most common source of post-return complaints.
On the compliance side the same flow carries its own paperwork. You get a withdrawal function compliant with Article 11a from 19 June 2026 even without an EU establishment, photo documentation that holds up in condition disputes and platform appeals, and product data ready for the PID obligation from 1 November 2026.
What to check about return shipping before you scale
- Does your returns policy state where exchanges and replacements physically ship from?
- Do you have a local return address in every EU country you sell in, and can you respond to a return request within two calendar days?
- Is your refund clock anchored to being informed of the withdrawal (as the law requires), or to a parcel completing an international journey?
- Does your policy make clear whether you accept returns when customers return products purchased online, and under what conditions?
- Does your policy clearly separate voluntary returns from eu consumer rights on faulty goods, including the conformity guarantee that is legally required under the eu consumer rights directive and european union law: if you sell goods to eu customers through an online store, they have a two-year guarantee for faulty goods even if you are established outside the EU, though implementation can vary by member state; and does it explain when you offer refunds beyond the statutory minimum?
- Is your withdrawal function two-step, available throughout the withdrawal period, and present on third-party platform orders too?
- If you sell digital services online, does your withdrawal wording cover them and handle them separately from physical returns?
- Do you have written grading rules (restock / outlet / donate / dispose / consolidate) and product data ready for PID?
How Shopreturns helps
- Local handling: return addresses and local carriers across key EU markets. That simultaneously satisfies the domestic return address requirement on marketplaces and stops automatic returnless refunds.
- Speed: verification within 48 hours (EAN scan plus photo documentation), which fits inside both the statutory 14-day refund window and platform response windows.
- Automation and customs: exchanges fulfilled from stock already inside the EU, so the replacement never generates another €3 duty. Everything else is consolidated into bulk shipments with clearance and Returned Goods Relief documentation handled.
- Integration: a ready One-Click-Return plugin compliant with the two-step Article 11a requirement, ERP integrations, and flexible disposition options (resale, donation, disposal).
Reviewing other businesses' return and refund policies can help benchmark customer-facing wording, but the final policy still needs to match the seller's own compliance setup.

FAQ
Do I have to change my returns policy because of the €3 duty? Legally you can keep it. Operationally you shouldn't: a policy that fulfils exchanges by shipping from outside the Union pays the duty on every exchange, and multiple times on multi-item orders. Your policy should also distinguish statutory withdrawal rights from any extra voluntary return window you offer, so customers can see the different time limits clearly.
Is the €3 charged per parcel? No. It is charged per item line, based on tariff sub-heading. An order containing three different types of product means three charges.
Why am I paying €3 when I'm selling from the UK or the US, not buying in the EU? Because the duty attaches to the import into the Union and is payable by the business - the seller, importer or their representative - not by the consumer on delivery.
How do I avoid paying the €3 on every exchange? Fulfil exchanges from stock already inside the EU, whether returned or held, instead of shipping a fresh replacement from outside as a new import.
Can I reclaim the €3 paid on goods a customer returned? Not automatically. Once the goods are released for free circulation, recovery requires a repayment or remission application with full supporting documentation. Model your reverse-logistics costs conservatively, assuming you won't recover the duty.
Can I still offer free returns after July 2026? Yes, and many brands do. But model it against your real reverse-logistics cost: a free return handled locally inside the EU is far cheaper than a free return shipped individually across a border.
Does the new withdrawal function extend the return window to 30 days or force free returns? No. Directive (EU) 2023/2673 changes neither the 14-day period nor who pays for return shipping. It requires only an easily accessible two-step electronic function and a confirmation of withdrawal, and your policy should also state clearly who covers the return shipping costs.
Do the 14-day withdrawal rules apply to all sales? No. The right applies to a sales contract concluded at a distance, not generally to in store purchases made in a physical store. This guide is written for a professional seller that may sell products cross-border, not a private individual making occasional sales, and a custom return policy or refund policy template can help create a legally compliant return approach aligned with EU law. It also covers withdrawal consumers in the EU-law cases for online digital content or service contracts, even though the return handling differs from physical goods.
Does the withdrawal obligation apply to me if I have no EU entity? Yes. What matters is whether you direct your offer at consumers in the Union, not where you are established. It also covers sales through third-party platforms.
How long does verification of a returned parcel take? Every parcel goes through full verification - EAN scan, visual inspection, photo documentation - within a maximum of 48 hours of delivery.
What to do before 1 November
A returns policy is a document; the cost is in the operation behind it. Every failure mode in this guide comes back to the same thing - the return, or the replacement, crossing a border it didn't need to cross. The €3 duty just made that crossing expensive enough to notice.
Three things are worth fixing in that order. Move exchange fulfilment to stock already inside the Union, so a replacement stops being a fresh import. Put a local return address in every EU market you sell in, so marketplaces stop making the refund decision for you. Get HS and PID data audit-ready before the declaration requirement lands on 1 November 2026, while the transition still runs without penalties.
Do those three and the policy wording becomes the easy part: withdrawal function, refund clock, grading rules and exchange terms all describe a flow that already works, instead of promising one you can't afford to run.
Not sure what your current setup is costing you?
Send us your numbers and we'll run them against the new regime - where the duty is hitting twice, what your return freight actually costs against the goods you recover, and how much of it is avoidable. One working session, and you leave with the figures either way.
Keep reading
More from the knowledge base
The First Black Friday Under the €3 Customs Rules
Where does your return parcel actually go? We tracked 31 British returns (Part 6)